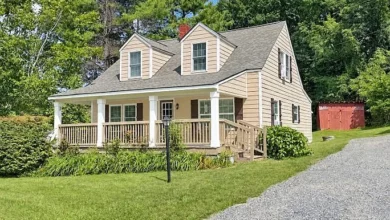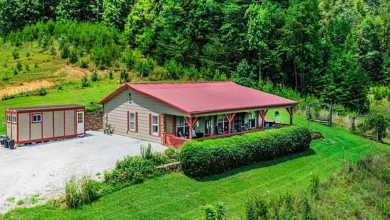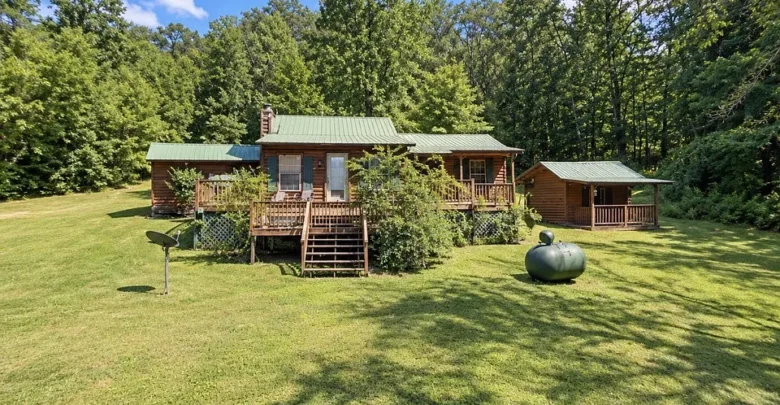
A bank-owned handyman special on 5.12 acres in Tennessee Ridge, Tennessee, with a creek, well water, a tornado shelter, and multiple outbuildings, offered as-is at $110,000.
Not every listing is meant for buyers who want to move in tomorrow.
Some are meant for people who see what a place could become.
At 203 Hurricane Creek Drive in Tennessee Ridge, Tennessee, a bank-owned home sits on just over five acres with a creek running through the land. It needs work. The bank is selling it as-is. But the land, the price, and the features already in place make it worth a close look.
Let’s go through it honestly, the good and the challenging.
Property Overview
- Price: $110,000
- Address: 203 Hurricane Creek Dr, Tennessee Ridge, TN 37178
- Bedrooms: 3
- Bathrooms: 1
- Living space: 1,487 square feet
- Year built: 1997
- Lot size: 5.12 acres
- Sale type: bank-owned, sold as-is
- Water: well
- Features: creek, tornado shelter, multiple outbuildings
What “Bank-Owned” Means
This property is owned by a bank, usually after a foreclosure.
Banks are not homeowners. They have never lived in the house, they don’t know its history, and they generally won’t make repairs. Their goal is to sell the property and move it off their books.
That is why bank-owned homes are often priced below the market. It is also why buyers need to be careful.
What “As-Is” Really Means
The listing says as-is more than once. Take that seriously.
As-is means the bank will not fix anything before closing. No repair credits. No negotiating a new roof or a working furnace. What you see is what you get, and sometimes what you don’t see too.
You can usually still inspect the home. You just shouldn’t expect the seller to act on what the inspector finds. The inspection is for your decision, not for a repair list.
The Price
At $110,000, the home works out to about $74 per square foot, with five acres included.
That is a low entry point for land with a house, a well, a creek, and outbuildings. The question is not whether the price is low. It is how much work the house needs, and whether the total cost still makes sense.
The Home
The home was built in 1997 and has 1,487 square feet of living space.
A late-1990s home avoids many problems of much older houses. You are less likely to find lead paint, knob-and-tube wiring, or old galvanized plumbing.
But the home is nearly 30 years old. Original systems from 1997 would be well past their expected lifespan.
Confirm the construction type. Some rural homes from this era are site-built, while others are manufactured or modular. That makes a big difference for financing, insurance, and resale.
The Bedrooms
The home has 3 bedrooms.
Three bedrooms is the most popular layout for buyers and renters alike. That gives this property wide appeal once it is fixed up.
Look at each room’s condition. Check the floors, ceilings, and closets for signs of water damage or neglect.
The Bathroom
There is just one bathroom.
For a three-bedroom home, that is the biggest layout weakness. Families and renters both prefer at least two baths.
At 1,487 square feet, there may be room to add a second bathroom, perhaps a half bath or a small primary bath. Adding a bathroom is one of the best ways to raise value on a home like this. It also needs plumbing and septic capacity, so plan carefully.
The Kitchen
The listing does not describe the kitchen.
In a bank-owned home, assume the kitchen may need work. Appliances are sometimes missing, damaged, or not working. Cabinets and counters may be worn.
A kitchen refresh can range from simple paint and new hardware to a full replacement. Price it out before you make an offer.
The Living Areas
With nearly 1,500 square feet, the home has decent space for its price range.
When you walk through, picture the layout with fresh paint, new flooring, and good lighting. Many bank-owned homes look worse than they are because they are empty, dirty, and dark.
Cosmetic problems are cheap. Structural and system problems are not. Learn to tell them apart.
The Roof
The listing doesn’t give the age of the roof.
On a home built in 1997, an original shingle roof would be near or past the end of its life. Look for missing shingles, sagging, and water stains on ceilings inside.
A roof replacement is one of the biggest costs a buyer could face, so factor it into your budget.
Heating and Cooling
The HVAC system’s age and condition are unknown.
Bank-owned homes are often winterized, with utilities shut off. That can make it hard to test systems before buying. Ask the listing agent whether the utilities can be turned on for your inspection.
If the HVAC is original, plan for replacement.
Plumbing and Winterization
If the home sat empty through cold weather, pipes may have frozen.
Look for winterization stickers or notices. If the home was properly winterized, the plumbing was drained to protect it. If not, there could be burst pipes inside the walls.
A pressure test of the plumbing system is worth asking for.
Electrical
Check the electrical panel and wiring.
Vacant homes can be targets for copper theft. Also look for signs of amateur repairs or missing fixtures.
Flooring
Flooring in bank-owned homes often needs replacing, especially carpet.
Luxury vinyl plank is a popular choice for flips and rentals because it is affordable, waterproof, and durable.
The Well
The home is served by well water.
A private well means no water bill. But a well that has sat unused can have problems.
Test the water for bacteria and contaminants. Have the pump and pressure tank checked. Ask whether the well has been disinfected recently.
Replacing a well pump is a common cost, but much cheaper than drilling a new well.
The Septic System
The listing doesn’t mention sewer, so the home very likely uses a septic system.
Have it inspected and pumped. A failed septic system can be one of the most expensive repairs on rural property.
Also check its permitted capacity if you plan to add a bathroom or bedroom.
The Tornado Shelter
The property includes a tornado shelter.
Middle Tennessee sees severe storms, especially in spring. A storm shelter gives real peace of mind for families. It is also a feature that adds appeal when you sell or rent.
Check the shelter’s condition. Look for standing water, a working door, and safe access.
The Outbuildings
The property has multiple outbuildings.
The listing doesn’t describe them, so see them in person. They could be sheds, a workshop, a garage, or a small barn.
Outbuildings add a lot of value on rural land. They give you storage for tools, mowers, and equipment, and room for hobbies or small animals.
Check their condition. Some may be worth fixing, while others may need to come down.
The Creek
A creek runs through the land.
It is one of the most attractive features here. Running water adds beauty, sound, and wildlife. It gives kids a place to explore and animals a natural water source.
The road name, Hurricane Creek Drive, suggests the creek may have a name of its own. Ask about flooding history and whether any part of the property falls in a flood zone. That affects both insurance and where you can build.
The Land
The property covers 5.12 acres.
Five acres is a sweet spot for many buyers. It is enough room for a big garden, chickens, goats, or a couple of horses, without being too much land to maintain.
It also gives privacy from neighbors and space for future projects.
Walk the land. Look at how much is cleared, how much is wooded, and how the ground slopes.
Restore or Rebuild?
The listing invites buyers to bring their vision or restore the home to its former glory.
That leaves two main paths.
You can restore the existing home. If the structure is sound, this is usually the cheaper path.
Or, if the house has serious problems, you could consider a new build on the land, using the existing well, septic, and utilities where possible.
Get a contractor’s opinion before deciding which way to go.
Living Here as an Owner-Occupant
For a handy buyer, this could be a chance to own five acres and a creek for far less than a move-in-ready home.
You could live in the home while fixing it room by room, if it is safe and livable. That approach takes patience, but it lets you build equity with your own work.
Once finished, picture mornings by the creek, a garden in the cleared ground, and a workshop in one of the outbuildings.
Investor Potential
The listing is aimed directly at investors.
There are a few common strategies here.
Fix and flip. Buy, renovate, and sell. Rural homes on acreage with a creek tend to attract strong interest when finished.
Buy and hold. Renovate and rent long-term. Three-bedroom homes are always in demand among renters.
Live-in flip. Live in the home while renovating, then sell later.
Any of these only works if the numbers add up. Price, repairs, holding costs, and the final value all matter.
Running the Numbers
Many investors use a simple rule. Take what the home would be worth after repairs, subtract the repair cost, subtract a profit margin and selling costs, and see if the purchase price still fits.
Look up recent sales of renovated homes on acreage near Tennessee Ridge. That gives you a realistic after-repair value.
Then get repair estimates from contractors, not just guesses. Underestimating repairs is the most common mistake on bank-owned properties.
Financing Options
Financing a bank-owned home in rough condition can be tricky.
Cash is often the strongest offer on bank-owned properties. Banks like quick, simple closings.
FHA 203k loans are designed for homes that need repairs. They combine the purchase price and renovation costs into one loan with a lower down payment.
Fannie Mae HomeStyle renovation loans work similarly on the conventional side.
Conventional, FHA, VA, and USDA loans usually require the home to be livable and safe. If the home has missing systems or major damage, it may not qualify until repairs are done.
Hard money and private lenders are common for investors. They cost more but move fast and focus on the property’s potential.
If the home is a manufactured home, financing rules change again. Confirm construction type early.
Insurance
Insuring a vacant, as-is home can be difficult.
Standard homeowners policies may not cover a home under renovation or sitting empty. You may need a vacant home policy or builder’s risk coverage during repairs.
If any of the land sits in a flood zone near the creek, flood insurance may be required by your lender.
Get quotes before you close.
Possible Projects and Improvements
- Replace the roof if it is original
- Update or replace the HVAC system
- Add a second bathroom
- Refresh or replace the kitchen
- Install new flooring throughout
- Paint the interior and exterior
- Repair or replace the well pump
- Pump and inspect the septic system
- Repair or remove outbuildings
- Clear brush and open up the land
- Build a deck or porch facing the creek
- Fence a pasture area for animals
Questions to Ask Before Making an Offer
- Is the home site-built, modular, or manufactured?
- Can the utilities be turned on for inspection?
- Was the home properly winterized?
- How old is the roof?
- How old is the HVAC system?
- Does the well pump work?
- What size is the septic system, and where is it located?
- Has the creek ever flooded?
- Is any part of the land in a flood zone?
- What are the outbuildings, and what condition are they in?
- Are there any liens, back taxes, or code violations?
- What addenda or special terms does the bank require?
- Is there a recent survey?
Inspection Is Essential
On an as-is, bank-owned home, the inspection is your most important tool.
The bank won’t fix anything, and it likely won’t give you a seller’s disclosure with the home’s history. The inspector is the person who tells you what you are really buying.
Order a full home inspection. Add a well inspection, water test, and septic inspection. If anything looks structural, bring in a structural engineer.
Also order a title search and title insurance. Foreclosures can sometimes leave behind liens or title issues that you don’t want to inherit.
Spending a few hundred dollars on inspections can save you thousands.
Tennessee Ridge and the Area
Tennessee Ridge is a small town in Middle Tennessee, northwest of Nashville.
It has a quiet, rural character, surrounded by hills, woods, and farmland. Daily needs are covered locally, while larger shopping and services are a drive away.
Clarksville and Nashville are within driving distance for city trips, jobs, and airports.
The Tennessee River and Kentucky Lake region lies to the west, offering fishing, boating, and outdoor recreation.
Tennessee also has no state income tax on wages, which keeps drawing buyers from other states.
The Price in Context
At $110,000, this is one of the more affordable ways to own five acres with a house in Middle Tennessee.
Bare land alone of this size can sell for a good portion of that price in many parts of the state. Here you also get a well, likely a septic system, outbuildings, a storm shelter, and a 1,487-square-foot home to work with.
But low price and low total cost are not the same thing. Add realistic repair costs before you decide whether this is a bargain.
Who This Property Is For
Investors looking for a value-add project on acreage.
Handy buyers willing to put in work in exchange for equity.
Buyers with cash or renovation financing who can close as-is.
Anyone who wants five acres and a creek at an entry-level price.
Final Thoughts
203 Hurricane Creek Drive is not a move-in-ready home. The bank is clear about that.
But it offers something many buyers want and can’t afford. Five acres, a creek, a well, outbuildings, and a storm shelter, at a price that leaves room for renovation.
Go in with your eyes open. Inspect everything, price your repairs carefully, and make sure the numbers work.
For the right buyer, this could be the start of a great comeback story.


View the full listing on Zillow
Our website is designed for informational and entertainment purposes only. We are not a real estate brokerage or licensed contracting service. We operate solely as an independent blog, curating interesting houses, DIY guides, and practical home tips found across the internet. All decisions related to real estate transactions or home renovations should be made in consultation with licensed professionals. We do not guarantee the ongoing accuracy or availability of external property listings, as market statuses change rapidly. Please use our content at your own discretion.